
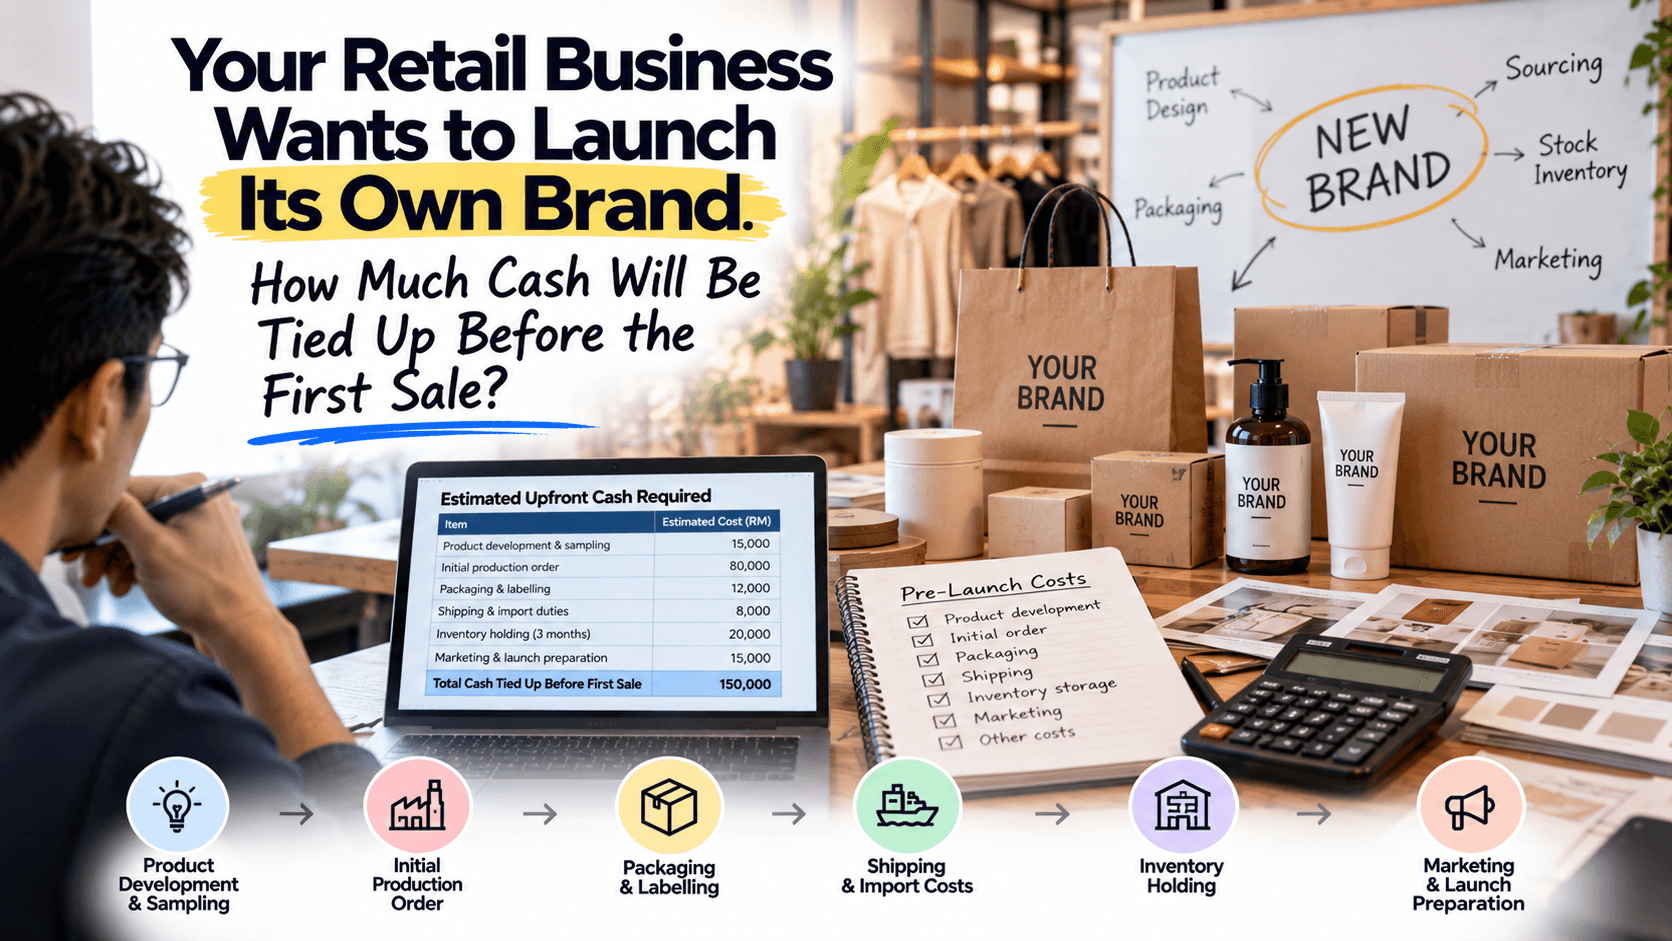
You already know which products sell well in your stores. Customers trust your recommendations, and a manufacturer has offered to produce a similar range carrying your own brand. The proposed purchase price looks attractive compared with what you currently pay established suppliers.
It is easy to start calculating the potential margin. However, launching your own brand changes more than the label on the product. Your business may need to pay for samples, packaging and production months before customers can buy anything. You may also have to order more stock than you would normally hold.
The first financial question is how much cash must leave the business before sales begin. The next is how long it will take to recover that cash while continuing to pay rent, employees and existing suppliers. A launch can offer a promising margin and still place significant pressure on the retailer funding it.
Start With the Commitments Behind the Unit Price
A manufacturer’s quotation often gives prominence to the price per unit. That number is useful, but it needs to be read alongside the conditions attached to it. Minimum order quantities, payment milestones and packaging requirements can have a greater effect on the initial cash commitment than a small difference in price.
Establish whether the minimum applies to the whole order or separately to each product, size, colour or fragrance. A range of five variants may require five individual production commitments. Packaging suppliers may impose their own minimums, leaving you with unused boxes or labels after the first batch is completed.
Clarify which items are included in the quotation. Product development, samples, tooling, testing and transport may be charged separately. Ask whether sample revisions or production changes create further fees.
Prepare a schedule showing each commitment, its payment date and whether it can be cancelled or reduced. This turns an attractive quotation into a clearer picture of what the business would actually be agreeing to fund.
Map the Spending Before Products Reach the Shelf
The cash requirement starts before the main production order. Design work, sample evaluation and packaging development may need to be paid for while the product is still being refined. Several rounds of revisions can extend this stage and increase spending without creating saleable stock.
Then consider the steps between production and launch. There may be inspections, freight, handling, storage and product photography. Your business may also need shelf displays, website changes or additional fulfilment arrangements.
Where the product category requires particular testing, labelling or approvals, establish the applicable requirements and obtain realistic cost estimates before committing. The requirements vary by product, so a budget copied from another retailer’s launch may omit important work.
Keep launch spending visible even where it is paid through existing departmental budgets. If marketing absorbs the photography cost and operations pays for storage, the project can appear cheaper than it really is unless those amounts are brought together.
Build a Simple Pre-Launch Cash Example
Consider a hypothetical retailer planning an own-brand home accessory. The first order is 5,000 units at S$8 each, including the agreed retail packaging. The total production price is S$40,000, with a 40% deposit and the balance payable before dispatch.
The retailer budgets S$6,000 for design, samples and initial checks, S$4,000 for freight and handling, and S$5,000 for photography, displays and launch advertising. Assume all these amounts are paid before the first customer receipt. The total pre-launch cash outflow is S$55,000.
The S$16,000 production deposit is part of the S$40,000 order value, not an additional cost. The remaining S$24,000 becomes payable later. Keeping that distinction clear prevents the deposit from being counted twice or the final balance from being overlooked.
This simplified example excludes taxes, financing costs and the existing business’s normal operating payments. Those items would need their own place in a real cash forecast. The S$55,000 is therefore a project starting point, rather than a complete estimate of how much cash the retailer needs in the bank.
The example also shows why deposit affordability is an incomplete test. Being able to pay S$16,000 today does not establish that the business can fund the balance and all the spending required to launch.
Separate Cash Committed From Cash Already Paid
At any point in the project, the bank balance shows only the payments that have occurred. It does not show every obligation management has already accepted. A production order may commit the business to a substantial balance even while most of the cash remains in its account.
Maintain a schedule of unpaid commitments alongside actual spending. Include approved orders, scheduled production balances and agreed launch services. Identify any conditions that could change the amount or timing.
This matters when several products are being developed at once. Each project may look manageable on its own, while their final payments fall due in the same month. A combined view helps prevent different teams from committing the same available cash to separate activities.
Update the schedule whenever specifications, quantities or delivery dates change. A revised purchase order should flow into the financial plan immediately, rather than waiting until the invoice reaches the accounts team.
Distinguish Product Margin From Cash Recovery
Suppose the product in the example is expected to sell for S$20. Comparing that price with the S$8 production cost produces an appealing spread. However, that spread does not account for every cost involved in getting the product to the customer.
Payment processing, promotions, fulfilment, returns and other selling expenses may reduce the amount retained. Some customers may also buy at discounted prices, meaning the average realised selling price is lower than the displayed price.
For a further simplified illustration, assume each unit sold produces S$17 in cash after variable selling outflows, before ongoing overheads and tax. Recovering the S$55,000 pre-launch outlay would require receipts from approximately 3,236 units on that basis.
That is a project cash-recovery illustration, not an accounting profit calculation. It assumes no additional project spending, refunds or replenishment payments and does not provide for the wider business’s bills. Its purpose is to show that an attractive unit margin does not mean the initial cash returns quickly.
Forecast Sales by Product, Not Just by Brand
An overall sales target can hide an uneven range. One product may sell quickly while another remains on the shelf, particularly where customers prefer specific sizes, colours or formats. Cash tied up in the slow items cannot automatically fund replenishment of the popular ones.
Prepare an initial sales forecast for each meaningful variant. Use evidence from existing category sales, customer feedback or a limited trial where available. Recognise that demand for an established brand does not necessarily transfer at the same level to your new label.
Be explicit about the assumptions. If the forecast depends on customers switching from a familiar product, explain why you expect that switch and how you will assess it. If it depends on attracting new shoppers, include the planned cost of reaching them.
A smaller initial range may make the launch easier to fund and evaluate. The relevant comparison is between the cash required, the information gained and the commercial opportunity, rather than the visual appeal of launching many products at once.
Allow for a Slower Start
Launch plans often assume that sales begin immediately after stock arrives. In practice, photography may be delayed, products may require further checks, or customers may take longer to respond than expected. Stock can be available without generating the forecast receipts.
Prepare a slower-sales scenario as well as the expected case. Consider what happens if the first three months produce only part of the planned volume or if launch moves back several weeks. Identify which payments can be delayed and which are already committed.
Assess the practical response before spending begins. Would management reduce advertising, narrow the range or postpone another order? Would those actions preserve cash, or would they undermine the activity needed to sell the existing stock?
Set a reserve based on the exposure shown in the forecast. A round-number contingency may be convenient, but it is more useful to understand which delays and additional payments it is intended to cover.
Remember That the Second Order Can Arrive Early
A successful launch can create a new cash pressure. If manufacturing and delivery take several months, the retailer may need to place a repeat order while much of the first batch remains unsold.
For example, strong sales of one variant might trigger another production deposit before the total range has recovered its initial cash outlay. The business then has money tied up in slow stock from the first order and in production for the next one.
Model the reorder point and payment terms alongside the sales forecast. Include lead times, stock needed during that period and any minimum quantity required for replenishment. A forecast that ends at the first sale or first delivery misses this part of the funding requirement.
Discuss whether staged deliveries, smaller repeat orders or revised payment terms are commercially available. Assess the full effect of those options, including any price increase, rather than assuming that the lowest unit price produces the best cash outcome.
Protect the Retail Business That Is Funding the Launch
The new brand will often be financed by an existing retail operation. That business still needs stock for established lines, enough employees to serve customers and cash to meet its regular commitments. A launch budget should reflect those competing demands.
Prepare a consolidated cash forecast showing the project alongside the existing business. Look at the lowest expected cash balance and when it occurs. Include scheduled supplier payments, payroll and other obligations rather than treating the current bank balance as entirely available for investment.
Consider whether the new product replaces sales you already make. If customers switch from an existing line, the financial benefit is the change in contribution and cash requirements, not the full value of the new product’s sales. Avoid forecasting the old and new ranges as though both will retain the same customers independently.
Management should agree how much the established business can commit and what would trigger a pause. That limit gives the project team a practical boundary when additional spending requests arise.
Use Approval Stages to Control Further Spending
Not every launch decision needs to be made at once. Management can approve sample development first, review the results and then decide whether to commit to production. Later stages can depend on quality acceptance, confirmed delivery arrangements and readiness to sell.
For each stage, identify the evidence required and the next cash commitment. Sample approval should establish that the product meets the intended specification. Production approval should also consider the forecast, supplier terms and funds available.
Keep responsibility clear when changes are proposed. A packaging revision that appears minor to the design team may create obsolete materials or restart a supplier’s minimum order requirement. Someone needs to assess that financial effect before approval.
The aim is to make further spending deliberate. Clear stages give management opportunities to address problems while some commitments are still avoidable.
Track the Launch With Records That Explain the Result
Once trading begins, track purchases, stock movements, discounts, returns and selling costs consistently. Separate the new brand in management reporting where practical so that its performance does not disappear inside the retailer’s overall sales.
Keep the cash view alongside the accounting results. Product purchases, deposits and launch expenditure may be treated differently in the accounts, so total cash paid should not simply be labelled a current-period expense. Equally, a favourable reported margin does not establish that the project has recovered its funding.
Review actual results against the assumptions used to approve the launch. Look at realised selling prices, the performance of individual variants and the timing of repeat orders. Those findings should guide further purchases and spending decisions.
Lee & Hew provides accounting, bookkeeping and management accounts services for businesses, including retailers. Organised financial records can give owners a clearer basis for assessing an own-brand launch and understanding its effect on the wider business.
Before committing to production, establish the full amount payable before sales, the likely timing of cash recovery and the additional funding that replenishment may require. Those figures help turn a promising product idea into a launch the business can afford to support.