
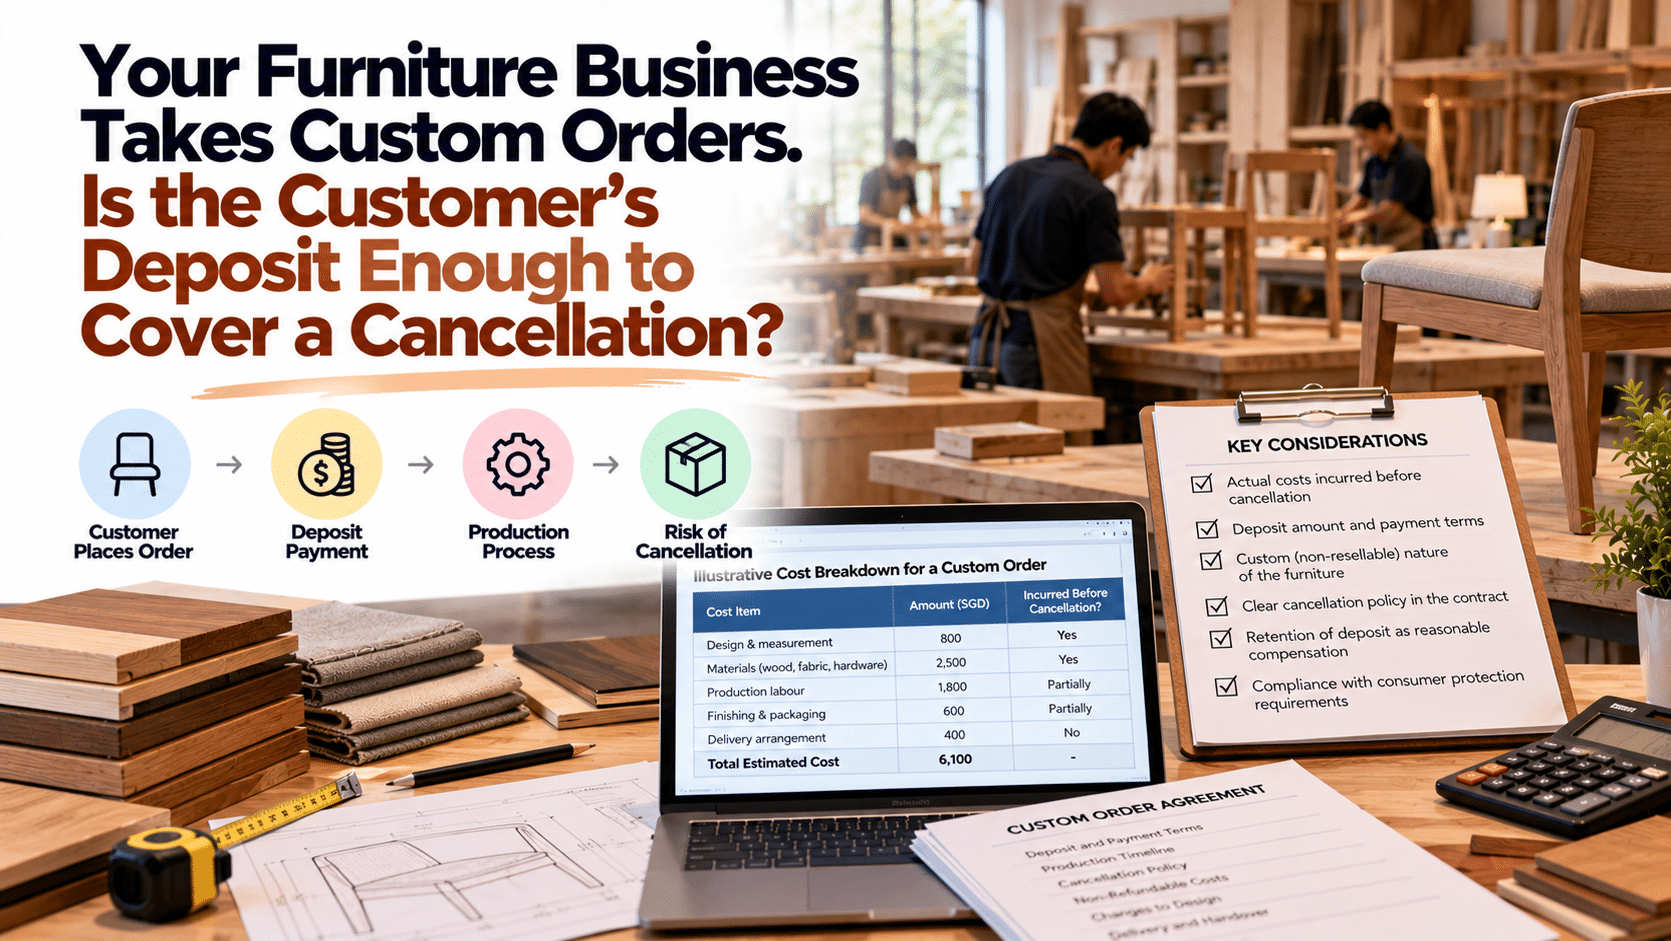
A customer approves a custom dining table, chooses the timber and pays the deposit. Your team orders the materials, books workshop time and begins preparing the components. A few weeks later, the customer’s renovation is delayed, the required dimensions change or the order is cancelled altogether.
The deposit provides some protection, but whether it covers the financial exposure depends on what your business has already committed. Standard timber may be usable elsewhere. A stone top cut to unusual dimensions or personalised upholstery may be much harder to recover value from.
Lee & Hew provides accounting, bookkeeping and management accounts services. For a furniture business, clear job records can help connect customer collections with material purchases, fabrication spending and outstanding commitments. That information gives the owner a stronger basis for setting payment milestones and deciding when production should proceed.
The starting question is how much the business would be left funding if the order stopped at each stage. A deposit percentage becomes meaningful only when it is compared with that exposure.
Start With the Cost of Stopping the Order Today
The selling price includes more than the spending incurred before delivery. It may cover design, materials, fabrication, installation, overheads and the intended profit. A deposit calculated as a percentage of that price does not automatically match the costs exposed at a particular stage.
Prepare a simple cancellation review for representative orders. Identify spending already incurred, additional amounts that remain payable and any costs that could still be avoided. Then assess what could realistically be recovered from materials or unfinished work.
Keep this financial assessment separate from the legal question of what the customer owes. The amount the business has spent does not automatically establish a right to retain the entire deposit or charge the customer an additional sum.
Review the agreed terms and obtain appropriate legal advice where retention, refunds or cancellation charges are uncertain. The costing exercise supports the commercial discussion; it does not determine enforceability.
Recognise That Different Custom Orders Carry Different Exposure
A dining table made in a standard size may be easier to sell to another customer than fitted cabinetry designed for a particular room. Both are custom orders, but their cancellation consequences differ.
Consider the features that limit alternative use. These might include unusual dimensions, personalised engraving, distinctive finishes or components designed around the customer’s existing fixtures. Some choices become difficult to reverse much earlier than others.
Supplier arrangements also matter. A readily available material purchased from stock may be returnable, while a specially manufactured component may require full payment once production starts.
Use these differences when reviewing payment terms. A single deposit percentage across every product may be administratively convenient, but it can leave the most specialised orders carrying the greatest unsecured exposure.
Map the Points Where Commitments Increase
Custom furniture production normally involves several decisions rather than one continuous commitment. The customer approves a design, materials are ordered, cutting begins, assembly follows and installation is scheduled.
Identify when each step creates an additional obligation. Accepting a supplier order may commit your business to more than the deposit paid to that supplier. A subcontractor may also become entitled to payment once a particular instruction is given.
Keep a schedule showing the amount paid, the unpaid commitment and the cancellation conditions. This prevents management from treating the bank payments to date as the full exposure.
Lee & Hew’s bookkeeping and reporting services are relevant to organising these financial records. The furniture team still needs to provide the operational milestones so that finance can explain when commitments arise and how they relate to the customer’s payments.
A Deposit Can Cover One Stage and Fall Short at the Next
Consider a hypothetical S$20,000 custom order with a 30% customer deposit of S$6,000. Assume that, at an early stage, job-specific costs incurred and unavoidable commitments total S$7,500.
The business expects to recover S$2,000 from returnable or reusable materials, after associated recovery costs. Its remaining cost exposure is therefore S$5,500. If the business is entitled to retain and apply the full S$6,000 deposit, that amount covers the identified exposure by S$500.
Now suppose fabrication progresses before another customer payment is collected. Incurred costs and unavoidable commitments rise to S$13,000, while expected net recovery falls to S$1,500 because the materials have been cut and customised.
The remaining exposure is now S$11,500. Against the same S$6,000 deposit, the business faces a S$5,500 shortfall.
This simplified illustration excludes tax, general overhead allocations and lost profit. It assumes no further recovery from the customer and no double counting between spending and commitments. It shows why a deposit that was sufficient at order acceptance can become inadequate later.
Measure Recovery Conservatively
A component’s original cost is not necessarily what the business can recover after cancellation. Uncut materials may have broad uses, while partially completed furniture may need additional work before another customer will consider it.
Separate different recovery routes. A supplier refund produces cash, a supplier credit supports a future purchase, and internal reuse may avoid later expenditure. Those outcomes have different values and timing.
Where resale is realistic, estimate the proceeds after completion, transport, storage and selling costs. Avoid assuming a second buyer will pay the original customer’s price for a design they did not choose.
Document the basis for significant estimates. Recent resale experience or a confirmed supplier return offer provides stronger support than a general belief that the workshop will eventually find a use for everything.
Do Not Count the Same Cost Twice
A cancellation schedule can become overstated if it adds supplier invoices, payments and outstanding balances without identifying their relationship. A S$4,000 invoice with S$1,000 already paid still represents a total obligation of S$4,000, not S$5,000.
Labour needs similar care. Direct job hours help assess the resources consumed, but a full labour allocation and a separate payroll charge may overlap. Explain whether the analysis measures job profitability, future cash payments or both.
Fixed workshop expenses require a separate view. Rent may continue regardless of the cancellation, while overtime booked specifically for the order may be avoidable if cancelled early enough.
Keep the calculation transparent. A reliable estimate of the actual exposure is more useful for pricing and negotiation than an inflated total that cannot be reconciled to the records.
Align Progress Payments With Meaningful Production Stages
A payment schedule can reduce the gap between customer collections and rising commitments. The appropriate milestones depend on the product and the agreed commercial arrangement.
For example, the business might request an initial payment when the order is accepted and another before an irreversible fabrication stage. A later payment could relate to completion or delivery, subject to the agreed terms.
The milestone should be clear enough for both parties to recognise. “Before production” is ambiguous if design work, supplier manufacturing and workshop assembly begin at different times. Describe the relevant stage and the evidence that will be provided.
Avoid selecting percentages simply because competitors appear to use them. Test the proposed schedule against your own costs, supplier terms and typical order timeline. The objective is a payment arrangement customers can understand and the business can deliver against.
Control Design Changes Before They Create New Spending
A customer may change the dimensions, materials or finish after approval without cancelling the order. The revised specification can still leave the business with unusable components and additional costs.
Record the requested change and assess its effect before proceeding. Identify extra materials, rework, supplier charges and any adjustment to the completion date.
Obtain the necessary agreement on the revised price and payment arrangements. A design team should not have to guess whether management intends to absorb a significant change as goodwill.
Keep the previous and revised approvals linked to the job. This supports accurate costing and helps explain why actual spending differs from the original quotation. It also reduces disputes about which version the workshop was authorised to produce.
Review Delays as Well as Cancellations
A postponed delivery can tie up cash even where the customer still intends to complete the purchase. Finished furniture may occupy valuable storage space while the final payment remains outstanding.
Identify how the agreed terms address delivery readiness, storage and revised dates. Discuss realistic arrangements before the furniture is completed rather than waiting until a customer cannot accept it.
Include the delay in cash planning. Materials and fabrication may already have been paid, while the expected balance moves into a later month. Several delayed orders can create a material funding gap.
The operational effect also matters. Storage congestion may interfere with new production or create extra handling. Record these effects so that future quotations and delivery arrangements reflect the actual cost of serving the order.
Keep Customer Collections Separate From Earned Profit
A deposit improves the bank balance, but it does not by itself establish the amount of revenue or profit earned. The accounting treatment depends on the contract, performance and applicable reporting requirements.
Finance should be able to distinguish customer advances, amounts billed, collections and the relevant revenue entries. A cancellation then needs a specific assessment rather than an automatic transfer of every retained amount into income.
For management purposes, maintain a separate view of available cash and the remaining work required on accepted orders. Cash collected from one customer may already be needed to fund that customer’s materials and production.
Clear reporting helps prevent new deposits from creating a false sense of surplus cash. The owner needs to understand the commitments attached to the order book alongside the money received.
Monitor Exposure Across the Whole Order Book
One order with a modest shortfall may be manageable. Several customised orders progressing ahead of customer payments can expose the business to a much larger amount.
Prepare an order-level report showing customer collections, costs incurred, unpaid commitments, production status and the next payment milestone. Highlight orders that have progressed beyond the expected collection stage.
Review concentrations as well. Several orders from one developer, designer or commercial client may be affected by the same project delay. Separate job numbers do not always mean independent risk.
Set internal escalation points that fit the business. A significant bespoke purchase or an overdue progress payment may require management review before further commitments are made. The response should follow the contract and consider customer communication rather than rely on an informal workshop decision.
Use Past Cancellations to Improve Future Terms
Completed and cancelled jobs provide evidence for refining the process. Review where the original cost estimate differed from actual spending and which components proved difficult to recover.
Look for recurring patterns. Perhaps unusual upholstery creates high exposure before assembly, or supplier cancellation charges arise earlier than the sales team expects. Those findings should influence future approval and payment stages.
Keep commercially successful orders in the review too. The objective is a workable process across the business, rather than terms designed only around the worst outcome.
A periodic review can also reveal that the issue is underpricing rather than the deposit alone. Collecting more money earlier does not make an unprofitable order profitable; it changes the timing and coverage of the funding.
Build a Clearer View of Custom-Order Commitments With Lee & Hew
A useful deposit policy connects the customer agreement with the production plan and the financial records. It shows when the business becomes committed, how much it could recover and what customer funds are available to meet the exposure.
Lee & Hew provides accounting, bookkeeping and management accounts support. For a furniture business, organised job-level records create a stronger foundation for reviewing these questions and monitoring commitments as orders progress.
Start with a small selection of representative orders and compare exposure at design approval, material purchase and fabrication. Use those findings to review the payment schedule, approval process and information management receives each month.
Contact Lee & Hew to discuss your accounting and reporting requirements. A clearer view of customer deposits and production commitments can help your business take on custom work with a better understanding of the cash and costs it is agreeing to carry.